Vail’s Busy Fall: More Choice for Buyers, Steady Closings, Prices Holding Firm
By Malia Cox Nobrega · Vail Market Reports · October 2026
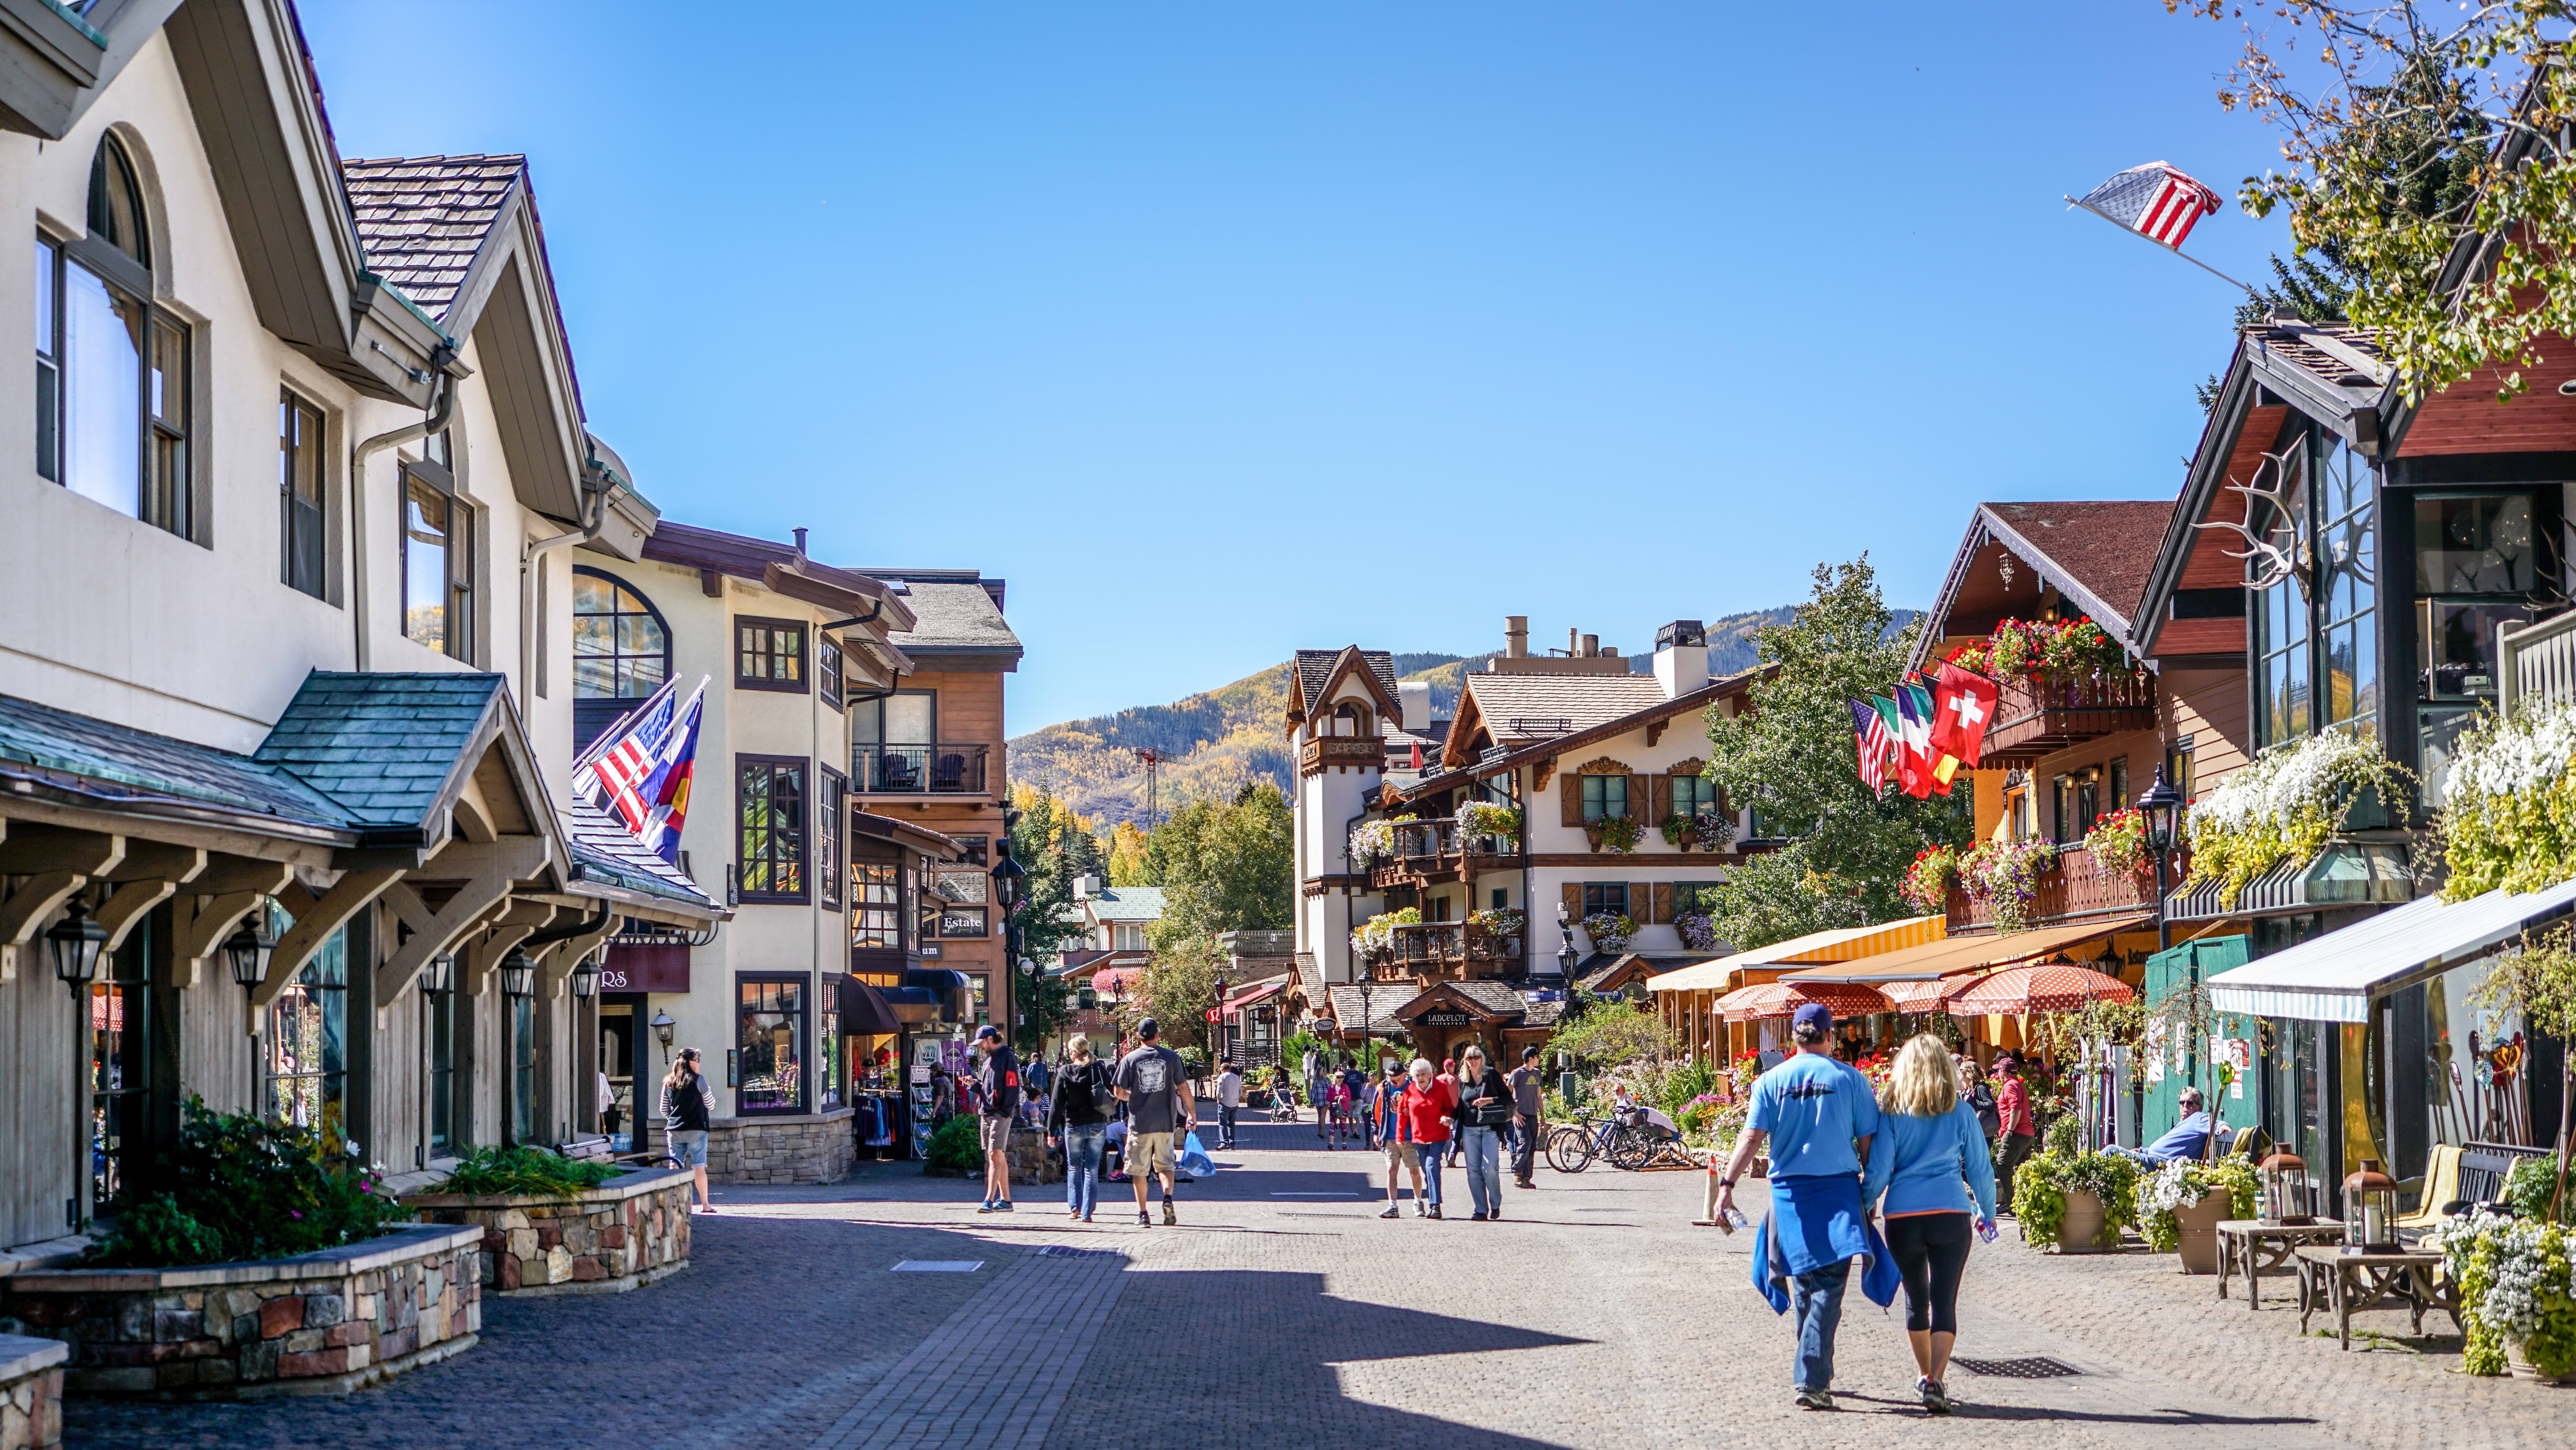
September opened the fall with a Vail real estate market that gave buyers far more to choose from while closings held near last year’s pace. It was a beautiful fall, and Vail was busier than ever; it barely felt like the off-season in Vail Village. Prices are holding firm overall, though micromarkets vary by location, price point and size, with some appreciating while others have not. The details are worth a closer look.
The broad market: steady closings, more to choose from
Across all residential property in the Vail Board of REALTORS® MLS, 101 homes closed in September against 103 a year ago, and pending sales came in at 92 against 104. The bigger change was on the supply side. There were 121 new listings in September, 55 percent more than last September, so buyers came into the fall with noticeably more to choose from. That is a healthy sign: the valley is moving closer to the more balanced inventory levels* it carried before the pandemic, giving buyers a better selection heading into the season.
Prices held through the steady month. The median sale price rose to $1.71M from $1.50M a year ago, while the average was essentially flat at $2.52M against $2.50M. A higher median with a flat average says more of the activity is happening in the middle of the market, not that values jumped across the board.
The year-to-date picture is the steadier read. Through the end of September, 697 homes have closed against 665 last year, up 4.8 percent. The median sale price is $1.59M, up 6.0 percent, while the average is $2.41M, down 6.9 percent, again because a greater share of sales is happening in the middle of the market rather than at the very top.
The number I watch most closely is how much of their original asking price sellers are receiving, because it captures every price reduction along the way. Year to date, homes are closing at 91.24 percent of their original list price, up from 90.10 percent a year ago. Sellers are pricing more realistically from the start, and buyers are meeting them closer to that number.
Residential Market Activity, All Price Points
The full Vail Valley market.
| September | Year to Date (Jan–Sep) | |||||
|---|---|---|---|---|---|---|
| 2025 | 2026 | % Chg | 2025 | 2026 | % Chg | |
| New Listings | 78 | 121 | +55.1% | 1,202 | 1,353 | +12.6% |
| Pending Sales | 104 | 92 | -11.5% | 751 | 791 | +5.3% |
| Closed Sales | 103 | 101 | -1.9% | 665 | 697 | +4.8% |
| Median Sales Price | $1.50M | $1.71M | +13.9% | $1.50M | $1.59M | +6.0% |
| Average Sales Price | $2.50M | $2.52M | +0.4% | $2.59M | $2.41M | -6.9% |
| Pct. of List Received | 95.50% | 93.89% | -1.7% | 95.12% | 95.07% | -0.1% |
| Days on Market | 83 | 95 | +14.5% | 77 | 96 | +24.7% |
| Active Listings* | 757 | 876 | +15.7% | 1,637 | 1,870 | +14.2% |
Residential homes at all price points. Current as of October 28, 2026. Sourced from the Summary Statistics Report in the Vail Board of REALTORS® MLS, all statuses included. *Active Listings reflect listings active at any point during the period, not an end-of-period snapshot. Days on Market is calculated on sold listings only.
Inventory: closing the gap to pre-COVID levels
Valley-wide, the market carried an average of 766 active residential listings* in September, up from 663 last September. That is real progress for buyers. It is also still below the valley’s longer-run norm. In 2017 through 2019, the last clean years before the pandemic, September averaged 903 active listings, and the valley typically carried roughly 800 to 950 listings across the year. This September sat about 15 percent below that pre-COVID September level.
The trend matters more than any single month. Inventory bottomed out in 2021 at roughly a third of its pre-pandemic level*. This year the gap to pre-COVID levels has narrowed from about 35 percent below in January to about 20 percent in July, 17 percent in August and 15 percent in September. Even so, this September’s 766 listings are still fewer than the valley carried in its quietest month before the pandemic. Supply is coming back gradually and steadily toward a healthier level, not all at once.
Supply and demand, 2019 to 2026
Homes sold (bars) and average active inventory (line), January through September each year, Vail Board of REALTORS® MLS, residential
The $5M-plus market: a busier month, a more selective year
At the top of the market, September was busier than a year ago: 12 closings against 8. The valley’s top sale of the month was 825 Forest Road #2 in Vail, a 4,573-square-foot, five-bedroom duplex that closed at $14.8M. The median luxury sale was $6.57M against $7.40M a year ago, and the average was $7.59M against $11.05M, which reflects which homes happened to trade in a small sample rather than a change in values.
Year to date, 69 homes above $5M have closed against 78 last year, down 11.5 percent, while the number of $5M-plus listings on the market at some point this year rose 12.1 percent. Fewer transactions against more inventory is the defining feature of the luxury market in 2026. What stands out is how well pricing has held through it. Luxury homes that sold this year closed at 89.79 percent of their original asking price, against 87.88 percent a year ago. Sellers at this level are pricing with more discipline, and the homes that are priced well are selling on better terms than they did last year.
Luxury Market Activity, $5M and Above
The top of the market, month and year to date.
| September | Year to Date (Jan–Sep) | |||||
|---|---|---|---|---|---|---|
| 2025 | 2026 | % Chg | 2025 | 2026 | % Chg | |
| New Listings | 10 | 15 | +50.0% | 153 | 166 | +8.5% |
| Pending Sales | 14 | 13 | -7.1% | 90 | 89 | -1.1% |
| Closed Sales | 8 | 12 | +50.0% | 78 | 69 | -11.5% |
| Median Sales Price | $7.40M | $6.57M | -11.2% | $7.88M | $7.00M | -11.1% |
| Average Sales Price | $11.05M | $7.59M | -31.3% | $9.79M | $8.79M | -10.2% |
| Pct. of List Received | 94.65% | 92.09% | -2.7% | 93.49% | 93.44% | -0.1% |
| Days on Market | 127 | 116 | -8.7% | 181 | 140 | -22.7% |
| Active Listings* | 129 | 149 | +15.5% | 248 | 278 | +12.1% |
Residential homes listed at $5M and above. Current as of October 28, 2026. Sourced from the Summary Statistics Report in the Vail Board of REALTORS® MLS, all statuses included. *Active Listings reflect listings active at any point during the period, not an end-of-period snapshot. Days on Market is calculated on sold listings only. Monthly figures rest on twelve closed sales, so read the year-to-date columns as the signal.
By price band: growth under $5M, patience at the top
Splitting the year to date into three price bands shows the shift clearly. The market under $5M is growing, and the slowdown is concentrated at the very top.
| Closed Sales | Pending Sales | |||||
|---|---|---|---|---|---|---|
| 2025 | 2026 | % Chg | 2025 | 2026 | % Chg | |
| Under $5M | 587 | 628 | +7.0% | 661 | 702 | +6.2% |
| $5M to $10M | 52 | 51 | -1.9% | 58 | 63 | +8.6% |
| $10M+ | 26 | 18 | -30.8% | 32 | 26 | -18.8% |
Year to date, January 1 through September 30 of each year. Bands are set by listing price. Sourced from the Summary Statistics Report in the Vail Board of REALTORS® MLS, residential, all statuses included, current as of October 28, 2026.
Closings under $5M are up 7 percent. Between $5M and $10M they are essentially even with last year, down about 2 percent, and above $10M they are down about 31 percent. Pending sales are up about 6 percent under $5M and about 9 percent between $5M and $10M, while pending sales above $10M are down about 19 percent.
The very top of the market is still working its way back from last winter. Through May, closings above $10M were running 40 percent behind last year. Through September, that gap stands at about 31 percent, close to where it was in August.
What is behind it: one tough winter
Last winter explains much of what we are seeing this year. The 2025-26 season was the thinnest this valley has seen since 1976-77, and it was thin across the Rockies, not just here. It also brought on a drought year, which didn’t help. The buyers most able to choose where they spend a season, the ones who own several homes, largely spent it somewhere else. That makes sense: when a season is as tough as last winter was across the Rockies, the ultra-wealthy have more options than anyone, and that shows up most clearly in the luxury closing count.
Other luxury ski markets lived through the same winter, and their numbers show it. In Aspen-Snowmass, sales above $10M are down 26 percent this year, close to our 31 percent, and in Jackson Hole they fell from 14 to 8 in the first half. Aspen’s third quarter has already turned, with $10M-plus sales up 44 percent over last year’s. Park City is the exception, and the agents I talk to there all say the same thing: the AI boom is bringing new wealth to the Salt Lake area, and Park City is where those buyers want to be. Away from the mountains, where winter was not a factor, the ultra-wealthy kept buying: on the island of Palm Beach, single-family closings nearly tripled in the third quarter at a $12M median, and on Martha’s Vineyard, sales above $10M rose from one to six in the first half. The appetite for the top resort markets is intact. Last winter simply moved it.
It was a single season, and it did not change what makes this place valuable. Our late summer was gorgeous, and our fall has been beautiful, with the considerable moisture that has been anticipated and expected. We are heading into winter with a lot of enthusiasm. The outlook has the Rockies favored for above-normal precipitation this winter under a very strong El Niño, so I am looking forward to a truly redemptive season. It is worth remembering that the last winter of similar levels, 1976-77, was followed by the best snow this valley had ever seen, a record that stood for 34 years until 2011.
What it means for buyers and sellers
For buyers, the valley hasn’t offered this much choice since before the pandemic*, including more homes above $5M than a year ago, and the pace now leaves room for a thoughtful decision instead of a rushed one. Homes priced right are still trading close to their original asking price, so today’s advantage is selection and timing, not deep discounts. If you’d like to be settled in before the snow arrives, now is the time to look. With a very strong El Niño building, we expect people to come back to the mountains this winter with real enthusiasm after many sat out much of last season.
For sellers, the message is about pricing. The homes that are closing are the ones priced correctly from the start, move-in ready, or truly rare, and the numbers show buyers are willing to pay close to the asking price when it is right. With inventory still below its pre-pandemic level*, a well-positioned home continues to stand out.
Data note: Figures are from FlexMLS Summary Statistics for the Vail Board of REALTORS® MLS (entire MLS), residential property (single family, duplex, triplex, townhouse, condominium), all statuses, current as of October 28, 2026. Luxury figures are homes listed at $5M and above. Year-to-date figures cover January 1 through September 30 of each year. Figures cover actively listed MLS sales. Sister-market figures come from each market’s own published reports and may define price bands differently (our bands are by listing price). All figures should be verified independently.
*Inventory figures are the average number of active residential listings across each month, from FlexMLS Market Statistics for the entire Vail Board of REALTORS® MLS. The pre-COVID benchmark is the 2017 through 2019 average for the same calendar month, so each month is compared like for like. The Active Listings row in the tables is a different count: every listing active at any point during the period, not a monthly average.
Malia Cox Nobrega
Malia Cox Nobrega is a luxury real estate advisor with LIV Sotheby’s International Realty in the Vail Valley, ranked among the top 100 agents globally within the Sotheby’s International Realty network year after year, consistently among the top 25 real estate agents in Colorado, and a multi-year RealTrends Verified top 300 agent nationally. Her practice spans premier new construction and luxury resale across Vail, Avon, the Beaver Creek Resort area, Edwards, and Red Sky Ranch in Wolcott.
See Malia’s current listings · Get the monthly market report by email